

Fidelity Investments

- 57.53K Reviews
- 4.1
- Downloads
- 5,000,000+
Our take on Fidelity Investments from Appgk
When I first open Fidelity Investments, I do not see a narrow trading tool aimed only at active investors. I see a finance app built to bring investing, saving, and planning into one place, which makes it especially interesting for someone who wants to start carefully rather than jump straight into complicated market activity. The app is free, is intended for everyone, and comes from Fidelity Investments, a developer with a long presence in personal finance.
That broad purpose is both its main attraction and its first challenge. A beginner can use one app as a starting point for learning how different financial tasks fit together, but the number of choices may feel less comfortable than a simple savings app. My experience is that the app works best when I arrive with one clear goal: check an account, understand where money is going, begin investing, or review a longer-term plan. Trying to explore every area at once makes the first session feel busier than it needs to be.
Getting comfortable before making a financial decision
The app has been available since December 15, 2010, and its current version is 4.39. Those details matter less than the practical impression: this is not a temporary experiment or a single-purpose budgeting utility. It is a mature financial application, and that maturity shows in the amount of information it expects users to handle. I would not install it expecting a two-minute tour and nothing more. I would install it when I want a continuing place to manage several parts of my financial life.
Fidelity Investments is free to download, but “free” should not be confused with “risk-free.” The app can help me view information and take financial actions, yet the decisions themselves still require attention. Investing involves choices about goals, time horizons, and tolerance for losses. I appreciate that distinction because a polished interface can otherwise make a serious decision feel like an ordinary tap on a phone.
Best Parts of Fidelity Investments
Things to Keep in Mind About Fidelity Investments
The app has an average rating of 4.1 from around 220 thousand ratings and more than 58 thousand written reviews. Its install count is above 5 million, so it is clearly used by a substantial audience. I read those figures as a sign of familiarity rather than a guarantee that every user will love the experience. Finance apps are personal: a feature that feels reassuring to one person can feel cluttered or overly detailed to another.
Before I begin, I decide what “success” means for the first session. For a new user, that might be completing setup and locating the account overview. For someone already using Fidelity elsewhere, it might be confirming balances and finding the right place to review investments. For a person considering a first contribution, success may simply mean understanding the path without submitting anything prematurely. Setting that boundary is useful because it prevents curiosity from turning into an accidental financial action.
News and Features Related to Fidelity Investments

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo

News
Moovit Review: A More Reliable Way to Navigate Everyday Transit

News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
What the first setup feels like
I approach setup more slowly than I would with a social or entertainment app. A finance app needs accurate personal information and secure access, so I keep my details available and avoid rushing through screens just to reach the home page. I also make sure I am using a private connection and a device I trust. That is not a criticism of this particular application; it is sensible behavior whenever an app connects me with financial accounts.
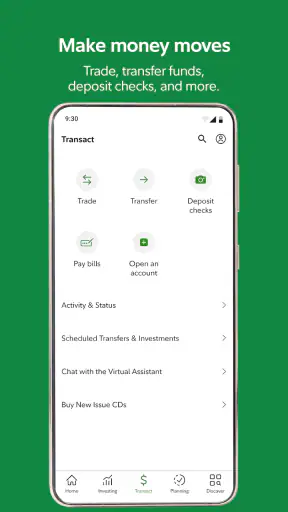
The first useful habit is to read each label before selecting an account or transaction area. Financial language can be similar while pointing to very different actions. “View,” “transfer,” “invest,” and “plan” should not be treated as interchangeable buttons. I find it helpful to pause after logging in and identify the screen that shows my overall position before opening more specialized sections.
Don't want to read the full review?
For a first-time user, the most reassuring route is to explore in layers. I start by learning where account information appears, then look at the tools related to saving or investing, and only afterward consider planning features. This order gives me a mental map. If I begin with a detailed investment screen, I can easily mistake technical information for a recommendation or assume that every visible option is something I should use immediately.
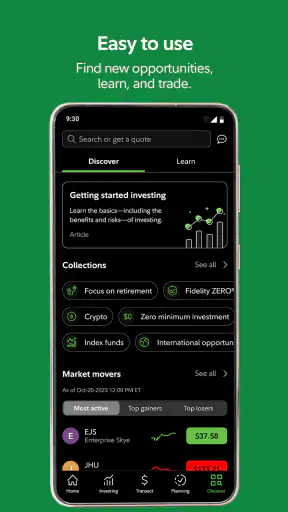
One of the app’s strengths is that it can serve different levels of experience. A person who has never invested can use it as a place to become familiar with the vocabulary and workflow, while a more experienced customer may value having account information and planning tools close together. The trade-off is that beginners need to create their own pace. The app is not a substitute for deciding what I am trying to accomplish.
Screenshots
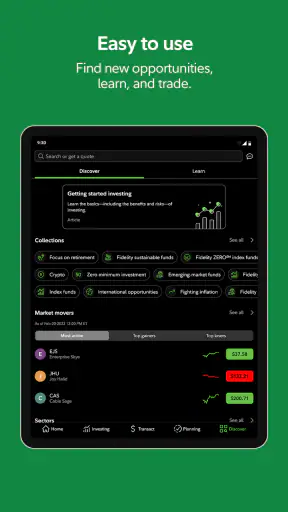
Finding a first meaningful success
My preferred first action is deliberately low pressure: sign in, confirm that the account information looks familiar, and locate the area I expect to use most often. That may sound modest, but it creates confidence without forcing a purchase, transfer, or investment decision. Once I know where the important information lives, later actions become easier to evaluate.
A realistic everyday scenario would be checking my finances during a lunch break after receiving a regular paycheck. I might open the app to see whether my current plan still matches my goals, review the relevant account area, and make a note of one question I need to answer later. The value is not necessarily completing everything from the phone. The value is reducing uncertainty and turning a vague intention—such as “I should start saving more”—into a specific next step.
For someone ready to invest, I recommend separating research from execution. First, use the app to understand the available information and identify the account or investment area involved. Then stop and consider the amount, time horizon, and purpose of the money. Only after that would I return to complete an action. This two-visit workflow is slower than tapping through immediately, but it is a practical safeguard against making a decision because the interface made it convenient.
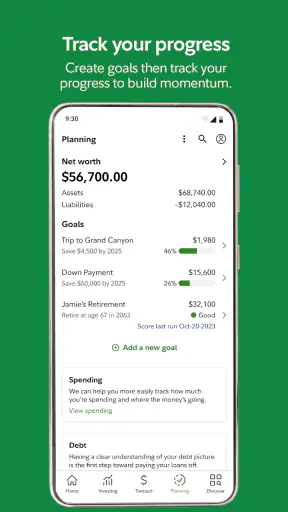
Another useful approach is to treat planning as a conversation with myself rather than a final answer. I can use the planning side to organize goals and see what information matters, then revisit the assumptions later. Financial plans change when income, expenses, or priorities change. I prefer an app experience that helps me return to those questions instead of encouraging a one-time declaration that I will never review.
The app is also well suited to people who want to connect short-term habits with longer-term thinking. Saving and investing are often discussed as separate activities, but using one financial environment can make the relationship easier to see. The important caution is that convenience does not remove the need to distinguish emergency money, near-term spending money, and money intended for a distant goal.
Where new users may feel confused
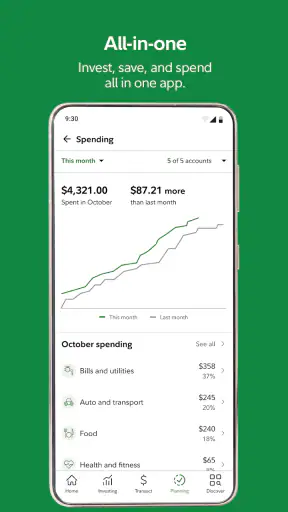
The biggest source of friction is not the basic idea of the app; it is the density of financial choices. A new user may wonder whether a visible balance represents available cash, invested money, or an amount connected to a particular account. I avoid guessing. I open the relevant details and read the surrounding labels before deciding what a number means.
Another common confusion is assuming that an account overview and a plan are the same thing. An overview tells me what is currently shown in the account environment, while a plan is about what I want my money to do over time. Keeping those purposes separate helps me avoid treating a current snapshot as proof that I am on track for a future goal.
I also would not assume that an attractive chart is an instruction. Charts can make changes easier to notice, but they do not automatically explain whether a movement matters for my situation or whether I should act. When I use the app, I regard visual information as a prompt for a question, not as a command. That mindset is particularly important for a first-time investor.
People moving from a basic banking app may also need time to adjust to the difference between saving and investing. A banking app often feels centered on spending and available cash. Fidelity Investments brings planning and investment decisions into the same experience, which is useful but requires more interpretation. If I only want to check everyday purchases or pay bills, a conventional banking app may be a better fit and less distracting.
Notifications and frequent checking can create another problem for anxious users. I do not believe looking at an account repeatedly improves a long-term plan. A better routine is to decide when I will review progress, then use the app during that window. This turns the phone into a tool for deliberate monitoring rather than a source of constant financial noise.
How it compares with simpler alternatives
Compared with a dedicated budgeting app, Fidelity Investments is stronger when the main question is how saving, investing, and planning relate to one another. A budgeting-first tool may be more comfortable for someone whose immediate priority is categorizing expenses or controlling monthly spending. I would choose the Fidelity app when I want a broader financial relationship, not when I need the simplest possible spending ledger.
Compared with a basic bank app, this application is more suitable for users who want to think beyond the next transaction. The advantage is having a more investment-oriented perspective alongside saving and planning. The disadvantage is that it can feel like too much if I only need deposits, transfers, and a quick balance check. For everyday banking alone, simplicity may matter more than breadth.
Compared with a specialized trading app, Fidelity Investments feels better aligned with a balanced, long-term approach than with constant market watching. Someone who wants advanced market tools, rapid execution, or a highly focused trading workspace may prefer a specialist platform. I would not select this app solely because I want the most intense trading interface. Its appeal is the wider financial context.
That comparison also explains who should skip it. I would look elsewhere if I wanted an app dedicated only to expense tracking, only to banking, or only to active trading. I would also hesitate if I knew I would feel pressured by seeing many financial options without understanding them. The right tool is the one that matches my actual behavior, not the one with the broadest menu.
Practical habits that make the app easier to use
My first tip is to create a one-purpose opening routine. Instead of browsing randomly, I decide whether I am checking, planning, saving, or investing before launching the app. That small decision reduces the chance of confusing information gathering with action. It also makes short sessions more useful because I know what I came to accomplish.
My second tip is to keep a written note of the questions that appear during setup. If I see a term I do not understand, I record it rather than making a guess. This is especially helpful when I am comparing account areas or thinking about a new contribution. Returning with a clear question is safer than allowing the app’s convenience to push me forward.
My third tip is to use a staged workflow for any meaningful change: review the goal, inspect the relevant account information, consider the consequences, and only then confirm the action. I find this particularly valuable on a phone, where a compact screen can make several steps feel like one continuous gesture. The extra pause is not wasted time; it is part of responsible use.
A fourth insight is that the app can be useful even when I do not complete a transaction. Locating information, understanding the difference between current status and future planning, and identifying what I need to learn are all legitimate outcomes. New users often measure success by whether they moved money. I think a better measure is whether they finished the session with less confusion and a clear next step.
Finally, I keep expectations realistic about mobile access. A phone is convenient for checking and beginning tasks, but a larger screen or additional research may be more comfortable when I am comparing choices or reviewing a complicated plan. The app does not need to replace every other financial resource to be valuable. It works best as a practical control point that I can return to regularly.
Who will get the most from it
I would recommend Fidelity Investments to a person who wants a free finance app from Fidelity Investments and prefers having investing, saving, and planning in a shared environment. It can be a good starting point for someone who is ready to learn gradually and wants more context than a basic bank balance provides. It is also useful for an existing Fidelity customer who values mobile access to financial information.
I would be more cautious recommending it to someone who wants instant simplicity. The app’s range is valuable, but range creates decisions. A first-time user should expect to spend some time learning the layout and terminology instead of assuming every screen will be self-explanatory. That is a manageable limitation, provided the user is willing to slow down.
The Everyone content rating makes it broadly approachable, but age suitability does not equal financial suitability. A person can be old enough to use the app and still need education before investing. I would encourage younger or inexperienced users to treat the app as a learning and organization tool first, and to discuss important decisions with a trusted, qualified source when appropriate.
Its audience size—more than 5 million installs—also means a new user is joining an established mobile experience rather than trying an obscure utility. Still, popularity should not decide whether it fits. The more important questions are whether I want Fidelity’s ecosystem, whether I need planning and investment features together, and whether I am comfortable taking responsibility for interpreting financial information.
My final view after using it
Fidelity Investments succeeds because it connects several financial intentions that people often keep in separate places. I can approach it as someone learning the basics, someone checking an established account, or someone trying to turn a broad goal into a more organized plan. The strongest experience comes when I use that breadth deliberately instead of treating the app like a simple balance checker.
There is a learning curve, and I would not hide it from a friend. The app can present more financial context than a beginner expects, and a phone screen is not always the ideal place to make a complicated decision. It also cannot decide how much risk I should accept or what goal matters most to me. Those are personal judgments, not interface problems.
My recommended path is straightforward: install it, complete setup carefully, find the account overview, explore one planning or investing area without committing to an action, and write down the next question you need answered. Once that feels clear, return for the first meaningful step. This approach makes the experience reassuring without pretending that investing is effortless.
With a 4.1 average from around 220 thousand ratings, a free price, and a current version of 4.39, the app is an accessible option for people who want more than everyday banking. I would choose it for a connected view of saving, investing, and planning, while choosing a simpler alternative for expense tracking alone or a specialist tool for highly active trading. For a first-time user, the best result is not tapping quickly; it is leaving the app with a clear goal, a better understanding of the next step, and no avoidable financial surprises.
Fidelity Investments FAQ
What is Fidelity Investments, and what can I do with the app?
Fidelity Investments is a financial services app for managing brokerage, retirement, cash management, and other eligible accounts in one place. After signing in, you can review balances and positions, monitor market information, research investments, place trades, transfer money, deposit eligible checks, and view statements. Available features can vary depending on your account type, location, device, and Fidelity’s current service policies.
Is the Fidelity Investments app safe to use for managing my money?
The Fidelity Investments app uses account authentication, encryption, security monitoring, and other protective measures designed to help safeguard personal and financial information. You should still use the official app-store listing, keep your operating system updated, create a strong unique password, and enable available multi-factor authentication. No online service can eliminate every risk, so avoid sharing login codes and review account activity regularly.
Can I buy and sell stocks, ETFs, mutual funds, or other investments through the app?
Yes, eligible Fidelity brokerage customers can generally research and trade a range of investments through the mobile app, including stocks, exchange-traded funds, mutual funds, and, where approved, options or other products. Trading access depends on account registration, permissions, market hours, and regulatory requirements. Investment values can rise or fall, and the app should not be treated as personalized financial advice.
Does Fidelity Investments charge fees for using the mobile app?
Downloading and using the Fidelity Investments app typically does not require a separate app subscription fee. However, account services, investments, transactions, margin borrowing, options activity, wire transfers, or other specialized features may involve costs or eligibility requirements. Pricing can change and may differ by product, so review Fidelity’s current fee schedule and trade confirmations before making financial decisions.
What should I know before opening or linking an account in the Fidelity app?
Opening or connecting an account may require identity verification, personal information, tax details, and funding information. The process can take longer if additional documentation is needed, and not every account type or external financial institution may be supported for linking. Before proceeding, confirm that you are using the official Fidelity app, understand the account terms, and consider whether the selected product suits your goals and risk tolerance.












